
Turn what you've built into the life you want.
I'm Alan Rhode, a fee-only financial advisor in Blue Bell, Pennsylvania, for executives, retirees and business owners. Whether what you've built sits in a company, company stock or a retirement account, I help turn it into money you can actually use. No products, no commissions, no Wall Street. Just someone on your side of the table.
30 minutes, by phone. No pitch, no obligation.
Find your stage
Where are you on the path to your next chapter?
Pick the one that sounds most like you right now, and I'll show you what I'd focus on first.
Tap the one that's you
The rest of this page changes to match: your stages, why clients like you choose me, the situations I handle and the calculators.
Showing the business owner view.Showing the executive view.Showing the retiree view. Not you? Tap yours above.
Now tap your stage
Sound like you?
Heads down and growing, and your wealth is piling up inside the business.
"Am I taking on risk I can't see? Shouldn't I be doing something smarter with what I'm making?"
The first move: start building wealth outside the business. Point at a part.
What I'd focus on first
- Build your first real financial plan, right alongside the business
- Set up the right company retirement plan to cut tax and reward your team
- Start moving wealth out of the business so it isn't all riding on one asset
- Make sure your growth builds transferable value, not just income
Sound like you?
Growing fast, and the financial side hasn't caught up to the business.
"We're scaling, but is my own financial life keeping pace, or just getting more complicated?"
Business and personal finances, brought back in step as one plan. Point at a piece.
What I'd focus on first
- Coordinate your business and personal finances as one financial plan
- Optimize your compensation and entity structure to cut tax
- Use retirement and benefit plans to reward and keep key people
- Plan around the personal guarantees and debt that growth puts in your name
Sound like you?
Most of your net worth rides on one asset, and that's started to worry you.
"If something happened to the business tomorrow, would the rest of my life be okay?"
A patient, tax-aware path to diversify out of concentration. Point at either side.
What I'd focus on first
- A patient, tax-aware path to diversify out of concentration
- Concentration and risk analysis across your whole balance sheet
- Protect what you've built, estate documents, insurance, liquidity
- An independent assessment of what the company is worth, and what is capping it
Sound like you?
A sale or transition is in view, and you only get this once.
"How do I read these offers, and keep more of what the business is worth?"
The bigger number is not always the better deal. Point at an offer.
What I'd focus on first
- Read the deal: third-party sale, family transfer, buy-out, or recap
- A value assessment and exit-readiness review, well before you sign
- Structure the transaction to minimize the tax bite
- Get your financial plan and retirement ready for the day the money lands
Sound like you?
The business sold. Now the money has to do the work the business did.
"What is all of this actually for, and how do I make it last?"
What is all of this actually for, and how do you make it last? Point at one.
What I'd focus on first
- Turn proceeds into reliable, tax-smart retirement income
- Roth conversions, gifting, and charitable strategies that fit your year
- Estate and legacy planning, kept current
- The harder question too: purpose, and the chapter you actually choose
Sound like you?
Your pay now comes partly in company stock, and it's growing faster than your plan.
“Do I sell when it vests? What am I supposed to do with these grants?”
A growing share of your pay arrives as stock. Point at a part.
What I'd focus on first
- Map every grant: what vests when, and what each one is worth
- Close the gap between tax withheld at vest and tax actually owed
- Set a simple rule for vested shares before they pile up
- Use your workplace plans fully: 401(k), ESPP and HSA
Sound like you?
Your income keeps climbing, and so does the list of choices nobody explained.
“Should I defer this bonus? Am I paying more tax than I need to?”
Each piece of your pay, decided together instead of one form at a time. Point at one.
What I'd focus on first
- Deferred comp elections matched to when you will need the money
- A multi-year tax plan for vests, exercises and bonuses
- Option exercises timed around taxes and the stock's risk
- Savings that keep pace with your income, not your lifestyle
Sound like you?
Too much of your net worth sits in one stock, and it's the company that also pays you.
“If the stock drops, I lose wealth and maybe my job at the same time. How do I get out without a huge tax bill?”
A patient, tax-aware path to move weight from one stock to everything else. Point at either side.
What I'd focus on first
- A target for how much company stock you hold, and a schedule to reach it
- Sell in a tax-aware order, using share lots, gifting and charitable giving
- 10b5-1 plans and trading windows, set up within your company's rules
- Protect the downside while you diversify
Sound like you?
A new job, a merger or an IPO is coming, and your equity is caught in the middle.
“What happens to my unvested shares, and what should I ask for before I sign?”
Each one changes what your equity is worth and when it is taxed. Point at one.
What I'd focus on first
- Know exactly what you keep, forfeit or accelerate
- Weigh a new offer on total after-tax value, not salary alone
- Track the deadlines to exercise options after you leave
- Handle lockups, severance and 401(k) rollovers
Sound like you?
You're ready to leave the corporate world, and your paycheck has to come from somewhere else.
“Can I really walk away? How do deferred comp and my stock turn into income?”
Three sources, one steady paycheck after the last corporate one. Point at one.
What I'd focus on first
- Turn deferred comp, stock and savings into steady retirement income
- Net unrealized appreciation (NUA) and rollover choices for company stock in your 401(k)
- Health coverage from your last day until Medicare
- Time Social Security and Roth conversions around your lower-income years
Sound like you?
Retirement is close enough to see, and you want to know the numbers really work.
“Do I have enough? When can I actually stop?”
The last working years are the cheapest time to close the gap. Point at either part.
What I'd focus on first
- A retirement projection built on what you really spend
- A retirement date, and what it depends on
- Catch-up savings and tax moves while you're still earning
- Pensions, Social Security and savings lined up as one income plan
Sound like you?
The paychecks are about to stop, and a handful of choices can't be undone.
“When do I take Social Security? Lump sum or pension? What about health insurance?”
Each is decided once, so each is run in numbers first. Point at one.
What I'd focus on first
- Time Social Security for you and your spouse
- Pension lump sum or monthly income, run in numbers
- Health coverage until Medicare, and Medicare enrollment on time
- Roll over workplace plans without losing what's worth keeping
Sound like you?
Your savings are now your paycheck, and you want it to last as long as you do.
“How much can I spend each year without running out?”
The right accounts, in the right order, every month. Point at one.
What I'd focus on first
- A monthly paycheck drawn from the right accounts in the right order
- Roth conversions in the lower-tax years before required withdrawals
- Keep Medicare premiums (IRMAA) in check
- An investment mix built for spending, not just growth
Sound like you?
Required withdrawals have started, and the tax bill is bigger than you expected.
“I don't even need all this income. Why am I paying so much tax on it?”
A required withdrawal can be split three ways. Point at a part.
What I'd focus on first
- Plan required minimum distributions years ahead
- Give to charity straight from your IRA with QCDs
- Watch the tax brackets and Medicare thresholds every year
- Keep the portfolio matched to what you still need
Sound like you?
You're comfortable, and the question now is what happens to everything after you.
“How do I take care of my family and the causes I care about, without leaving a mess?”
Everything you've built, pointed where you want it. Point at one.
What I'd focus on first
- Estate documents and beneficiaries, kept current
- Gifting and inherited-IRA planning so your heirs keep more
- A plan for long-term care costs
- Clear instructions so your family isn't left guessing
Quick check, about 10 seconds
You've done the hard part. Tap anything that still feels unsettled.
Tap as many as fit. Nothing is saved or sent.
0 of 6 sound like you.
For business owners, wealth isn't a portfolio problem. It's an optionality problem.For executives, wealth isn't a paycheck problem. It's a concentration problem.For retirees, the answer isn't a probability of success. It's “what's my monthly income, and when does it change?”
What I solve
NineEightSeven moving parts, one plan that keeps them working together.
You don't need another menu of services. You need someone to coordinate the moving parts you don't have time to orchestrate. Every area feeds the same plan. Explore any one to go deeper.
Coordinated, not bolted together
Ten areas, one plan
Every area connects to the same plan, so a move in your business and a move in your personal life are never made in isolation.

The person on your side
Hi, I'm Alan.
- 01Why I started
I started Modern Wealth in Blue Bell, Pennsylvania, after living the moment my clients now plan for. My father ran a solo dental practice that carried our whole family, and when he got sick I stepped in to keep the doors open, then led the sale so my mother would be okay. I know firsthand how much rides on decisions made at the worst possible time, and how few advisors are built to help. So I built the opposite: an independent, fee-only firm that earns nothing but the fee you pay me. No commissions, no quotas, no hidden agenda.
- 02What I bring
I'm a Penn State finance grad with more than 15 years in this work and a stack of credentials I actually use: Certified Financial Planner™ professional (CFP®), Certified Private Wealth Advisor® professional (CPWA®), Certified Value Growth Advisor® (CVGA®), Certified Exit Planning Advisor® (CEPA®), and Registered Life Planner® (RLP®). Along the way I've been named one of etf.com's Top 100 Financial Advisors (2024) and a Philadelphia Five Star Wealth Manager (2026). I hold the whole picture on one page. In plain English, I help you grow what your business is worth, plan a smart exit, and turn it into a life you actually want, not just a bigger account balance.
- 03Outside the office
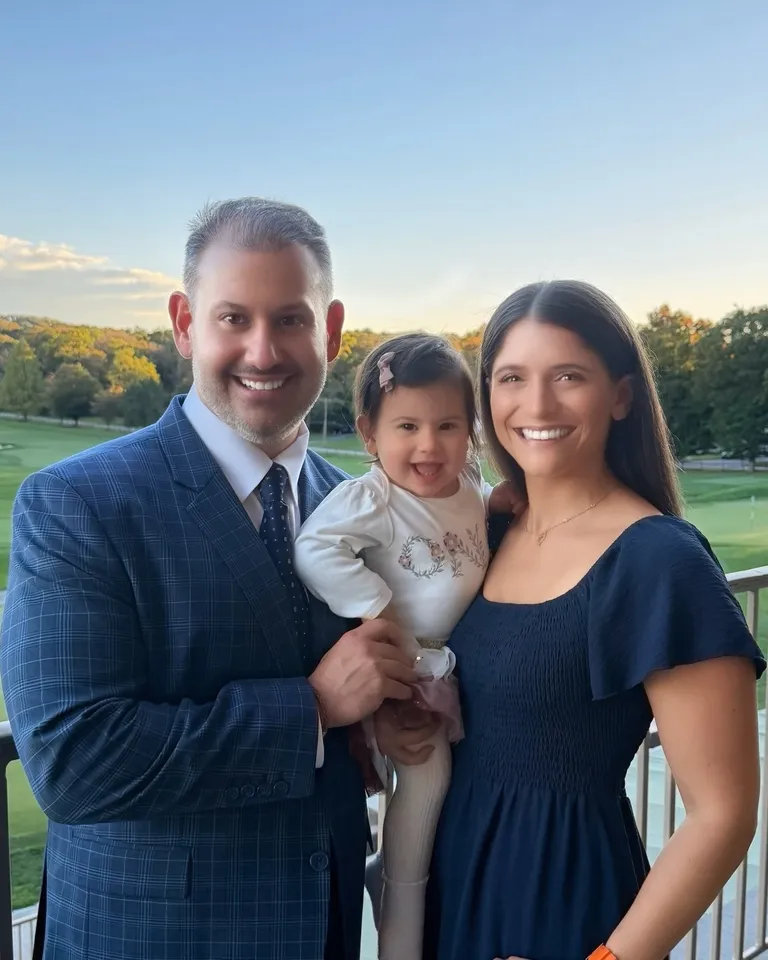
When I'm not doing that, you'll find me on an autocross course in my Miata, running the same clean line I bring to planning: look far ahead, stay smooth, don't chase the hero lap. Otherwise I'm cheering (and suffering) for Philly sports, or home in Blue Bell with my wife Jamie, our daughter Joey, and our goldendoodle, Enzo, the reason any of this matters. Money is a tool for building a life, and the life is the point. I'd genuinely like to hear your story.
Money is a tool for building a life, and the life is the point.
- CFP®
- CPWA®
- CVGA®
- CEPA®
- RLP®
Life outside the spreadsheet
The person you'll actually be working with.


Why owners choose meWhy executives choose meWhy retirees choose me
Three things most advisors can't do for an owner.Three things most advisors can't do for an executive.Three things most advisors can't do for a retiree.
The business
Your company is part of the plan, not just the sale
Most advisors start when the check clears. As a certified exit planner and value growth advisor, I look at what your company is worth, what holds that value back, and how to shape the exit in the years ahead, long before a buyer calls.
The equity
Your stock pay is part of the plan, not an afterthought
Most advisors manage what is already in the account. I plan your grants before they vest: RSUs, options, ESPP, deferred comp and 10b5-1 plans, timed around your taxes and how much of your wealth rides on one company.
The income
Your savings become a paycheck, not just a portfolio
Most advisors stop at the investment mix. I plan where each month's income comes from, when to claim Social Security, Roth conversions, required withdrawals and Medicare premiums, so more of what you saved stays yours.
The life
Your plan starts with your time, not your balance sheet
Registered Life Planner is a Kinder Institute credential. It's why our first real conversation is about how you want to spend your time, including life after the business, and why the whole plan is built backwards from that one answer.
The life
Your plan starts with your time, not your balance sheet
Registered Life Planner is a Kinder Institute credential. It's why our first real conversation is about how you want to spend your time, including when work becomes optional, and why the plan is built backwards from that answer.
The life
Your plan starts with your time, not your balance sheet
Registered Life Planner is a Kinder Institute credential. It's why our first real conversation is about how you want to spend the years ahead and who you want to spend them with, and why the plan is built backwards from that answer.
The wealth
Your whole financial life, in one plan
Your retirement, investments, taxes, estate and insurance, planned together instead of by five people. As a CFP® professional and Certified Private Wealth Advisor®, that plan is the core of what I do, built for an owner's balance sheet.
The wealth
Your whole financial life, in one plan
Your retirement, investments, taxes, estate and insurance, planned together instead of by five different people. As a CFP® professional, that full plan is the core of what I do, built for the complex balance sheets executives have.
The wealth
Your whole financial life, in one plan
Your retirement, investments, taxes, estate and insurance, planned together instead of by five different people. As a CFP® professional, that full financial plan is the core of what I do, built to last as long as you do, and longer.
In writing
Most advisors won't sign this. I will.
A fiduciary oath is a simple, binding promise to put your interest first, always, not just when it's convenient. If an advisor won't sign one, it's usually because they can't. You can download mine right here.
"A binding promise to put your interest first, always, and to disclose every conflict, in writing."
The evidence, minus the sales pitch
I can't show you testimonials. I'll show you the work instead.
As an independent, Pennsylvania state-registered fiduciary, I'm not permitted to use client testimonials or endorsements. So instead of reviews, here's what I can put in front of you: a real track record, the situations I work in every week, and credentials that change your outcome.
Business owners, professionals and their families, each working from one plan rather than a pile of accounts.
CFP®, CPWA®, CVGA®, CEPA® and RLP®: financial planning, private wealth, business valuation, exit planning and life planning.
Business value and succession, retirement plan services, executive compensation, investments, retirement, tax, estate, risk, cash flow and education, all coordinated as a single plan.
etf.com Top 100 Financial Advisors (2024) and Five Star Wealth Manager, Philadelphia (2026). Awards are not client endorsements, and the selection criteria are on the website disclosure page.
Situations I work in
The exit
An owner weighing three offers, two private-equity firms and a family business, who needed to read what each deal structure meant for their wealth, their taxes, and how much control they'd keep.
The practice
A specialist practice owner with a partner buy-out ahead, whose business value, company retirement plan, and personal taxes had never once been modeled as a single plan.
The concentration
A founder with nearly all of their net worth locked in the business and one account, and a patient, tax-aware path to diversify without handing a fortune to the IRS.
The next stage
A household with enough, and no plan for what enough was for. We put real numbers behind the things they had stopped saying out loud: time with the people they love, the trip that keeps getting postponed, and the work they would happily do for nothing.
The vest
An executive whose RSUs had quietly grown into most of their net worth, with tax withheld at 22% on income taxed at 37%, and a bill at tax time nobody had warned them about.
The offer
A senior leader weighing a move to a competitor, who needed to know what they were walking away from in unvested equity and what the new offer had to replace.
The concentration
A long-tenured executive with most of the household's wealth in employer stock, and a multi-year, tax-aware plan to bring it down without one giant tax year.
The next stage
A couple ready to step back early, who needed deferred comp payouts, stock sales and savings turned into one steady paycheck until Social Security and Medicare.
The transition
A couple choosing between a pension lump sum and lifetime income, and when each should claim Social Security: choices that could not be undone.
The income
Retirees with plenty saved and no plan for drawing it down, who needed a monthly paycheck from the right accounts in the right order.
The tax bill
A retiree whose required withdrawals pushed them into a higher bracket and higher Medicare premiums, and a plan built on Roth conversions and gifts to charity straight from the IRA.
The next stage
A household with enough, and no plan for what enough was for. We put real numbers behind the things they had stopped saying out loud: time with the people they love, the trip that keeps getting postponed, and the work they would happily do for nothing.
Run your numbers
Calculators for the questions business ownersexecutivesretirees ask me most.
Honest estimates, with the assumptions shown. No sign-up, no email.
Business Valuation
A value range for your business, based on the multiples buyers pay.
Open CalculatorBusiness Sale
What you actually keep from a sale of your business after fees and taxes.
Open CalculatorWealth Gap
Whether selling your business funds the life you want after you exit.
Open CalculatorS-Corp Salary
A reasonable S-corp salary, and how much payroll tax it can save you.
Open CalculatorRetirement Plan
Whether your savings will last, and how big the shortfall is if not.
Open CalculatorRoth Conversion
Whether paying tax now on a Roth conversion beats paying it later.
Open CalculatorBackdoor Roth
How much of a backdoor Roth is really taxable, and the move that fixes it.
Open Calculator401(k) Contribution
How much to save from each paycheck to reach this year's 401(k) limit.
Open CalculatorSocial Security
When to claim Social Security to collect the most over your lifetime.
Open CalculatorRequired Distributions
Your required minimum distribution this year, and in the years ahead.
Open CalculatorRoth Conversion
Whether paying tax now on a Roth conversion beats paying it later.
Open CalculatorRetirement Plan
Whether your savings will last, and how big the shortfall is if not.
Open CalculatorHow I charge
Transparent pricing, no surprises.
SixFourFour ways to work together, each a flat or tiered fee. No products, no commissions, ever.
One time
Financial Plan
From $2,000
Fixed fee, up to $5,000
A written plan for one decision or stage of life, with no ongoing commitment.
Ongoing
Investment Management
Up to 1% a year
No minimum
Your portfolio managed by a fiduciary, without ongoing planning.
Ongoing
Wealth Planning
From $6,000 a year
+ $2,000 one-time setup
A planner in your corner year-round, keeping the plan current.
Ongoing
Private Wealth Management
Up to 1.25% a year
$500,000 minimum
Your investments and your whole financial plan, coordinated by one advisor.
Ongoing
Wealth Planning & Business Advisory
From $12,000 a year
+ $4,000 to $6,000 one-time setup
The business and the household planned as one, from building value to the exit.
Ongoing
Retirement Plan Services
Up to 0.65% a year
Paid from plan assets
Fiduciary advice for your company's retirement plan.
How it works · the EVOKE® process
A clear path from "I'm not sure" to "I know exactly where I stand."
Five steps, each producing something you keep. No mystery, no obligation, you'll know if we're a fit before any paperwork.
- 01
Exploration
A 30-Min ChatA relaxed conversation about your goals and questions. I listen. I don't pitch.
- 02
Vision
One Page PlanWe get clear on what your money is for, and put what you want on one page.
- 03
Obstacles
Getting OrganizedAn hour organizing your wealth until everything is in one place.
- 04
Knowledge
Wealth PlanYour financial plan, and for owners, a value assessment, value acceleration, and exit plan.
- 05
Execution
Year-Round CadenceAn ongoing partnership: focused meetings through the year.
Let's have a real conversation.
Book a free 30-minute call. No pitch, no obligation, just a conversation about what you want and whether we're a fit. We talk by phone, so I work with owners here in Blue Bell and across the United States.
Book a Free CallFor referral partners
- CPAs
- Attorneys
- Insurance Agents
- Exit Planners
- Business Consultants
- Bankers
I collaborate around your client, not over the top of you, and I report back. I work alongside professionals across Montgomery County and Greater Philadelphia, and over Zoom with firms anywhere in the country. Send me a note and I'll walk you through exactly how that works.
Let's work together
Tell me a little about your practice and what you are looking for. I read these myself and reply personally.
Keep Reading
From the blog
Deferred Compensation Plans: How the Election, Payout and Risk Really Work
A nonqualified deferred compensation plan lets you put off pay, and the income tax on it, well beyond what a 401(k) allows. The trade is that you choose when it pays out years in advance, and the money stays a promise from your employer. Here is how the elections, payouts, taxes and risk work.
Read MoreHow Are RSUs Taxed? Why the Withholding Falls Short, and Whether to Sell at Vest
RSUs are taxed as pay on the day they vest, whether or not you sell. Here is how the tax works in 2026, why the 22% your company withholds is often thousands short, the cost basis mistake that really does tax you twice, and how I think about selling at vest.
Read MoreBlue Bell Owners Need More Than a Generalist Advisor
For a Blue Bell owner planning a sale, the right advisor is a fee-only fiduciary who coordinates valuation, tax and personal planning together, not one who only manages the portfolio after closing.
Read More